By Tyler Plack
Tyler Plack is the Chief Executive Officer of South River Mortgage. He joined the company as a founding employee in 2017 and served as President before becoming CEO in 2026. Tyler holds an active FHA Direct Endorsement (DE) underwriting certification.
A letter arrives asking you to fix something at home, but the next step is unclear. A reverse mortgage repair letter needs a careful read and a call to your loan company. Start by confirming what work it wants, when it expects action, and what proof to send.
In this article13 sections
- What Does a Reverse Mortgage Repair Letter Mean?
- How Can You Check Who Sent the Letter?
- What Should You Ask About the Repair List?
- Which Dates Should You Put on Your Calendar?
- How Can You Compare Repair Estimates?
- What If the Work Costs More Than You Can Manage?
- What Should You Save While Repairs Are Underway?
- What If the Contractor Finds Another Problem?
- How Do You Send Proof That the Work Is Done?
- How Do You Know the Repair Request Is Closed?
- Can an Adult Child Help With a Reverse Mortgage Repair Letter?
- What If the Letter Mentions Default or Foreclosure?
- The Bottom Line
What Does a Reverse Mortgage Repair Letter Mean?
The company that handles your loan is called your servicer. It may ask you to repair a problem that affects your home’s condition. Ask for a written list if the letter leaves the work unclear.
A Home Equity Conversion Mortgage, or HECM, is a reverse mortgage insured by the Federal Housing Administration. You must pay property taxes, homeowners insurance, and any homeowners association dues, and keep the home in good repair. It must remain your main home.
The Consumer Financial Protection Bureau explains these ongoing duties. A repair request does not replace your other loan duties.
- Read the whole letter, including any page attached.
- Find the repair list and any dates.
- Keep the envelope with the letter.
How Can You Check Who Sent the Letter?
Find the company’s contact details on a recent loan statement that you already trust. Use those details to ask whether it sent the letter. Avoid sending account details to an address you have not checked.
Keep the letter nearby during the call so you can read its exact wording. Ask the person to find the request in your account notes.
- Give the date shown on the letter.
- Ask which team handles the repair request.
- Write down the person’s name and the call date.
- Ask where you should send your reply.
If your loan company recently changed, review our guide to a reverse mortgage servicer change. Confirm who now handles the account before sending papers.
What Should You Ask About the Repair List?
Turn broad words into clear tasks before you ask anyone to price the work. A letter that says “fix porch” leaves plenty of room for confusion. Ask which part needs attention and what condition the company wants corrected.
For example, ask whether the request concerns a loose rail, damaged steps, or both. Ask whether there are photos or a report that explain the concern.
- Which exact parts of the home need work?
- What must be fixed for each item?
- Who can answer questions about the list?
- What papers or checks will show the work is complete?
Read your notes back during the call and ask for the answers in writing. Keep that reply with the original letter so you can compare the two.
Which Dates Should You Put on Your Calendar?
Look for separate dates for a reply, the start of work, and completion. Do not assume that one date covers every step in the process. Ask the loan company to explain each date shown on your letter.
Copy the dates onto a calendar you use each day. Add a reminder to check progress before a reply or repair is due.
- Record when the letter arrived.
- Record the dates stated in the letter.
- Ask about any date you do not understand.
- Keep written answers when a date changes.
A contractor’s open date may differ from the date your loan company expects. Tell the company about that gap rather than assuming the contractor’s schedule changes your deadline.
How Can You Compare Repair Estimates?
Give each contractor the same written repair list so the estimates cover the same work. Ask each one to describe materials, tasks, and the expected schedule. Compare what is included before choosing based on the total alone.
One estimate may include removing damaged wood while another includes only a new coat of paint. Those are different jobs, even when both mention the porch.
| Check This | Ask This |
|---|---|
| Work included | Does it address every item on the list? |
| Schedule | When can work start and finish? |
| Written terms | Do they match what you discussed? |
Keep each estimate with your notes so you can explain your plan clearly. Ask the loan company about any required review before signing a repair contract.
What If the Work Costs More Than You Can Manage?
Tell your loan company when cost is stopping you from making the requested repairs. Ask what information it needs to understand the problem and discuss next steps. Do not promise a start date that you know you cannot meet.
Your local Area Agency on Aging may know about home repair help for older homeowners. Ask which programs serve your area, what they cover, and how to apply.
- Keep the repair list ready when asking for help.
- Write down any papers a program needs.
- Ask about waiting lists and next steps.
- Keep your loan company informed about your search.
The Consumer Financial Protection Bureau describes repair help and steps after a default notice. Program availability and eligibility vary.
Check your eligibility
A few details to help us understand your options.
What Should You Save While Repairs Are Underway?
Use one folder to keep the repair list, estimates, contract, photos, and messages together. A paper folder works well if you prefer to keep printed copies. Add the date to each note before putting it away.
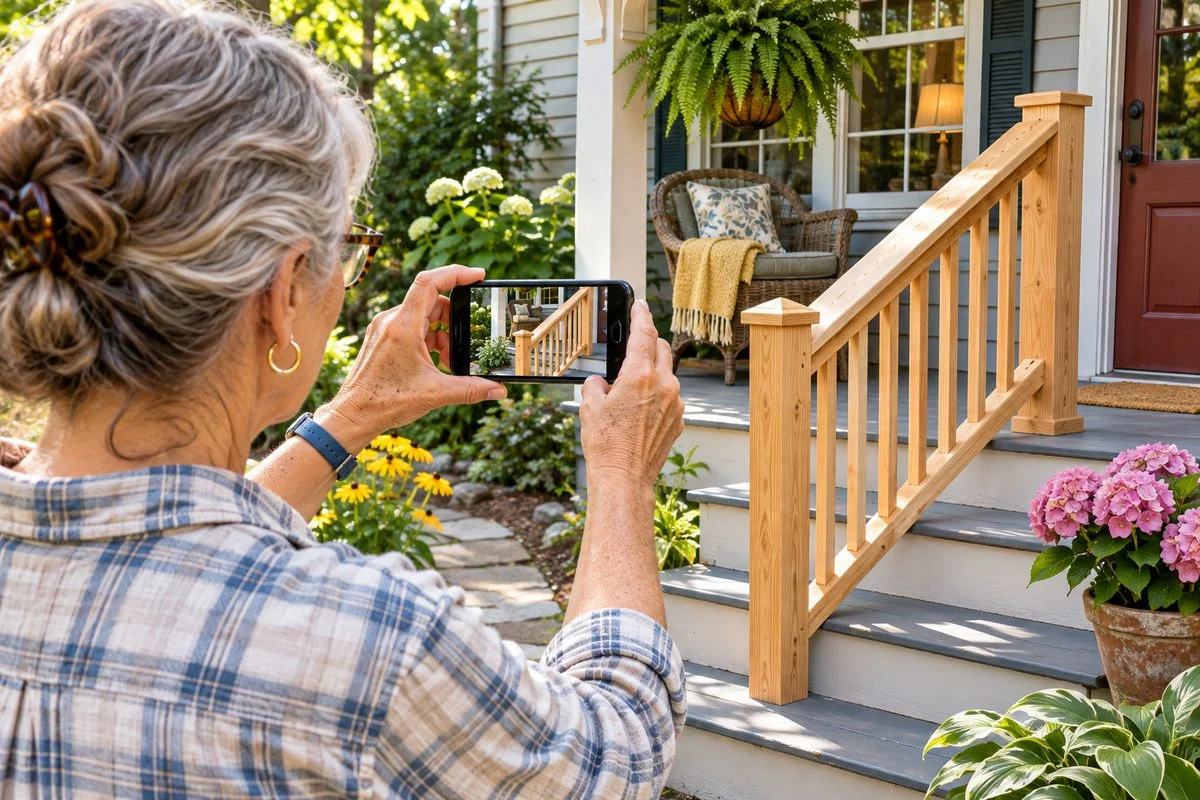
Take photos from a safe place when they help show the work being done. Ask the contractor for records of work you cannot safely inspect yourself.
- Save the agreed list of work.
- Keep receipts and any updated estimates.
- Save messages about delays or changes.
- Record questions that still need an answer.
These records help you explain progress without relying on memory during a phone call. Ask your loan company which records it wants rather than sending the whole folder at once.
What If the Contractor Finds Another Problem?
A contractor may uncover damage that was hidden when the first estimate was written. Ask for a clear description of the added work and an updated estimate. Keep the new details separate from the original list.
Call your loan company if the change affects the work it requested or the schedule. Explain what changed and ask what it wants you to send next.
- Which original repair is affected?
- What new work does the contractor propose?
- Will the finish date change?
- Does the loan company need a new plan?
For example, hidden rot may mean a railing repair takes longer than first expected. That is a reason to ask about the plan, rather than assume extra time has been granted.
How Do You Send Proof That the Work Is Done?
Ask your loan company how it wants to check each finished repair on the list. It may ask for papers, photos, or a further inspection of the work. Follow the instructions it gives for your account.
Label each item you send so the reviewer can match it to the repair list. Use a short cover note that names the repair and the enclosed proof.
- Check the requested mailing address or secure upload route.
- Send copies and keep your own full set.
- Save the mailing receipt or upload confirmation.
- Ask how to confirm the papers reached the right team.
A receipt shows that you sent something, but it does not show that the repair was accepted. Keep that distinction in mind when checking the account afterward.
How Do You Know the Repair Request Is Closed?
Keep your reverse mortgage repair letter until the response is clear. Ask whether the company has reviewed your proof and whether any items remain open. Request written confirmation of what it has accepted and what still needs attention.
If another letter arrives, compare it with your earlier request and your completion proof. Call to ask whether it concerns the same work or a different issue.
- Has each repair item been reviewed?
- Is another inspection needed?
- Are any papers missing?
- What is the next step, if any?
Use your call log to avoid starting the story from the beginning each time. A short list of dates and names can make the next conversation much easier.
Can an Adult Child Help With a Reverse Mortgage Repair Letter?
You can ask a family member to read the letter and organize your questions. Keep the borrower involved in the call and in decisions about the work. Ask the loan company what permission it needs before sharing account details.
A helper can sort receipts, label photos, and keep a calendar without guessing what the loan requires. Agree on who will make each call and save each reply.
- Choose one shared place for the repair records.
- Write down the questions before calling.
- Mark completed tasks on the same list.
- Keep private account details out of group messages.
For a useful way to build that file, see our guide to replacing lost reverse mortgage papers. Request copies if the original repair papers are missing.
What If the Letter Mentions Default or Foreclosure?
Read the notice and contact your loan company about the reason it gives. Default means the company says a loan duty has not been met. For legal questions about the notice or your options, talk with an attorney.
Ask a housing counselor approved by the Department of Housing and Urban Development, or HUD, for help understanding the situation. HUD-approved counseling is required before getting a HECM. A counselor can also help you understand where to seek help later.
A repair request does not change when the loan otherwise becomes due. Selling, permanently leaving the home, or the last borrower’s death can trigger repayment, subject to applicable spouse protections. A healthcare absence beyond 12 straight months can also trigger repayment when no co-borrower remains at home.
- Keep the full notice and its envelope.
- Ask what action the company says is needed.
- Do not assume sending a reply stops another deadline.
The Bottom Line
A reverse mortgage repair letter is easier to handle when you turn it into clear steps. Confirm the sender, get the work in writing, and keep track of dates. Save proof of the repairs and ask whether each item has been accepted.
Review the related recordkeeping guide above if you need help rebuilding your loan file.
For questions about a new loan, get an estimate on how much you may qualify for with our free reverse mortgage calculator or give us a call 855-212-9114. Our loan experts are ready to help.
No pressure. No obligation.