By Tyler Plack
Tyler Plack is the Chief Executive Officer of South River Mortgage. He joined the company as a founding employee in 2017 and served as President before becoming CEO in 2026. Tyler holds an active FHA Direct Endorsement (DE) underwriting certification.
Your daughter asks where you keep the loan papers if you ever need to leave home quickly. A reverse mortgage emergency plan puts useful copies and contact details within reach. Start with a small kit, then practice finding what you need together.
In this article12 sections
- What Goes in a Reverse Mortgage Emergency Plan?
- Which Loan Papers Should You Copy First?
- Who Should Be on Your Contact Sheet?
- Where Can You Keep Backup Copies?
- How Can You Practice a Call Before You Need It?
- What Should You Ask About Time Away From Home?
- Which Home Bills Belong on Your Reminder List?
- How Can a Family Member Help Without Taking Over?
- What Might a Simple Practice Run Look Like?
- What Changes if an Emergency Actually Happens?
- When Should You Check Your Reverse Mortgage Emergency Plan?
- The Bottom Line
What Goes in a Reverse Mortgage Emergency Plan?
Think of your plan as a guide to finding help and records. Your plan can fit in a slim folder without holding every paper you own. Choose the items you would want during a call away from home.
Begin with a recent loan statement, your insurance contact, and a trusted family contact. Add a note showing where you keep your full loan file. Keep private account details inside the pouch rather than on its cover.
- A recent statement and the loan company’s confirmed phone number.
- Your insurance company’s name, policy number, and claim contact.
- A short list of people you want to call.
- A note about where to find secure backup copies.
Build the kit on a quiet day when you can check each item, leaving space for details that need another phone call.
Which Loan Papers Should You Copy First?
Start with papers you can recognize and explain in a few words. A statement usually helps you find the company that handles your loan, called your servicer. Check that the company named there matches the name on your latest account mail.
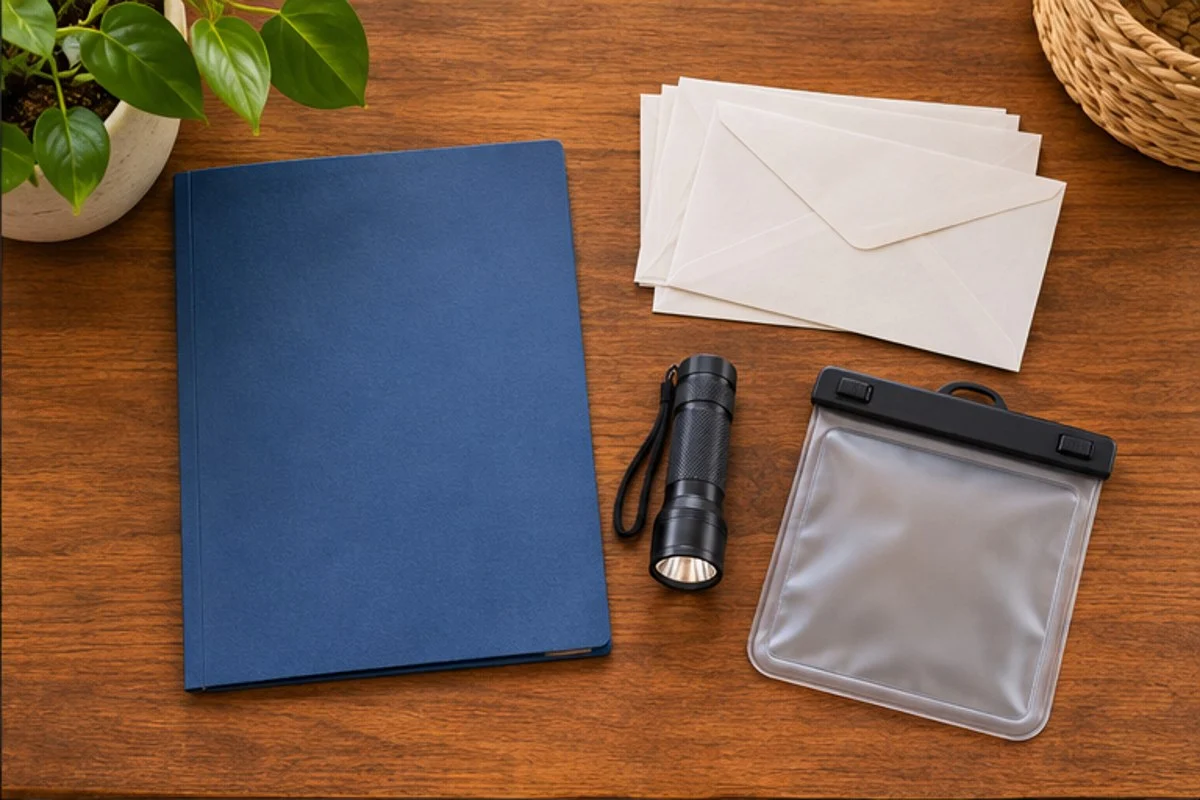
Make a simple contents list so another person can find each copy. You might group the statement, insurance page, and contact sheet behind separate dividers. Keep originals in their usual secure place while you assemble the copies.
- Check that every copied page is clear and complete.
- Include both sides when the back contains useful details.
- Write the date you checked the folder on its contents sheet.
If something is missing, use our guide to replacing lost reverse mortgage papers, and request the missing copy before you rely on the kit.
Who Should Be on Your Contact Sheet?
Label your loan company and insurance company on separate lines to help family members tell them apart. Add your own short note about the reason for each contact.
Use numbers from records you already trust, then check them before saving the sheet. Keep a paper copy so the list still works without your phone, and avoid putting passwords beside names and phone numbers on that sheet.
| Contact | Question to Prepare |
|---|---|
| Loan company | How should I report damage or a temporary absence? |
| Insurance company | Where should I send a claim question? |
| Trusted helper | Can you help me find copies and take notes? |
Ask a backup contact to help when your first helper is unavailable, then add their details to your private plan.
Where Can You Keep Backup Copies?
Choose a backup location you can reach when your main folder is unavailable. Keeping every copy in the same drawer gives you only one place to look. Ask yourself what you would do without access to that room.
The Consumer Financial Protection Bureau’s emergency preparation guide suggests keeping copies apart and protecting digital records. Use a storage method you already understand rather than rushing to learn a new one.
- Check that a paper pouch closes properly and protects its contents.
- Use a strong password for any digital storage you choose.
- Open a saved copy to check that you can read it.
Tell your chosen helper where to find the backup when you want help. Share only what that person needs for the role you agreed on.
How Can You Practice a Call Before You Need It?
Try a short practice call on a calm afternoon with your contact sheet nearby. Ask your loan company how it wants you to report an emergency. Write down the answer in your own words while you are talking.
Explain that you are organizing records before anything has happened, and ask which phone number and secure message route you should keep. Read the details back so you can catch a wrong digit or missing step.
- Find the current statement without searching through your whole file.
- Locate the confirmed phone number and your private account details.
- Ask how to report damage or a change in where you stay.
- Save the date, contact name, and answer with your plan.
If you do not understand an answer, ask for plain words or written instructions. A useful practice call leaves you with fewer questions about who to contact.
What Should You Ask About Time Away From Home?
Ask how to report a temporary stay elsewhere before you need that information. Keep the answer with your contact sheet rather than relying on memory. Describe the reason for the stay and ask what records the company needs.
For a Home Equity Conversion Mortgage, a federally insured reverse mortgage called a HECM, your main home matters. Selling, permanently moving out, or the last borrower’s death can make the loan due. Eligible spouses may have protections, so ask about your household’s situation.
- How should I explain a temporary stay away from the property?
- What updates should I send if my plans change?
- Where will account notices go while I am away?
A health-related absence lasting over twelve consecutive months can also make the loan due under applicable conditions. Do not assume that every kind of absence follows the same rule. For legal questions about your rights, talk with an attorney.
Check your eligibility
A few details to help us understand your options.
Which Home Bills Belong on Your Reminder List?
Keep a separate reminder sheet for bills tied to your home. List who sends each bill, where you find it, and who normally checks it. This helps you explain your routine if a family member helps temporarily.
The bureau explains your ongoing reverse mortgage duties. You must pay property taxes, homeowners insurance, and any homeowners association dues, and keep the home in good repair.
Add a reminder to ask who handles any payments taken from loan funds. Check the answer against your records rather than assuming everything happens automatically.
- Property tax notices and the place you keep payment records.
- Insurance renewal mail and your agent’s confirmed contact details.
- Association bills, if your home has them.
Keep loan-specific questions with your loan company and coverage questions with your insurer. A household reminder sheet helps organize those conversations without deciding the answers for you.
How Can a Family Member Help Without Taking Over?
Choose a task that matches the help you actually want from your family. You might want someone to find a copy, take notes, or sit beside you. Say which tasks you prefer to handle yourself during an account call.
Ask your loan company what permission it needs before discussing your account with someone else. A family relationship alone does not tell you what the company will share. Keep any confirmed permission steps with your private loan records.
- Agree on who holds the folder during a call.
- Ask your helper to repeat the next step back to you.
- Keep passwords and private account details away from group messages.
Practice with the actual person you hope will help, when possible. Let them ask where things belong so your system makes sense to both of you.
What Might a Simple Practice Run Look Like?
Imagine that you plan to stay with your daughter during a local power outage. This is a made-up household example, with no damage to the home. Your first task is finding the contact sheet and your recent statement.
Your daughter finds the folder, but the insurance number is difficult to read. You replace that copy and move the contact sheet to the front. Then you check that your secure backup opens on the device you would bring.
- Choose a familiar situation and talk through the first few steps.
- Find the copies without using your usual desk drawer.
- Check which details require a call before you leave.
- Update the folder after you notice a gap.
The point of practicing is to find small problems while you have time. You can stop after one useful fix and return to the rest later.
What Changes if an Emergency Actually Happens?
Put your safety first, follow local emergency directions, and do not return to an unsafe home to retrieve papers. When you can safely begin making calls, use the backup records you prepared earlier.
The bureau’s guide for reverse mortgage borrowers after a disaster explains contacting your loan company and insurer. It also explains that home damage does not erase your loan responsibilities. Ask both companies what they need for your situation and save their replies.
- Record who you spoke with and the date of each call.
- Keep copies of messages, letters, and any requested records.
- Ask when and how you should provide another update.
If you are still considering a new HECM, required counseling comes before the loan, as our guide to reverse mortgage counseling explains. Existing borrowers can also ask a housing counselor for help understanding loan concerns.
When Should You Check Your Reverse Mortgage Emergency Plan?
Choose a reminder that fits your household, such as reviewing your insurance renewal mail. Revisit the folder after a loan company change or a new phone number. Check it when your trusted helper changes, too.
Take out old working copies when you replace them with current ones. Keep historical records in your full file where you can find them later. Mark the kit’s review date so you know which version you last checked.
- Can you reach every contact on the current sheet?
- Does the statement show the company now handling your loan?
- Can your chosen helper find the folder when you ask?
A reverse mortgage emergency plan works best when it stays simple enough to use. Keep the next small update clear rather than waiting for a perfect filing system.
The Bottom Line
A reverse mortgage emergency plan brings copies, verified contacts, and family roles together before you need them. Start with the papers you have, then practice finding one record and making one call. Keep your home obligations in view and ask about any change in where you stay.
- For another useful step, read our guide to replacing missing loan papers before completing your folder.
Considering a reverse mortgage? Use our reverse mortgage calculator to explore the numbers, then discuss your questions with our reverse mortgage experts.
Call 855-212-9114. No pressure. No obligation.